
Listen to this article in summarized format
×
Subscribe to
Unlock AI Briefing and Premium Content
New Year Offer 24 Hours Left
Subscribe NowAlready a member? Sign In
What's Included
- Exclusive Stories
- Daily ePaper Access
- Smart Market Tools
- Curated Investment Ideas
- Ad-lite Experience
Subscription
 ET Online
On Diwali, many people buy physical gold in the form of jewellery, coins, bars, etc., as it is considered auspicious. Some also buy physical gold as an investment, believing that investing during the festival will bring them luck. However, when you invest in gold, the key is not just to look at gold’s price appreciation; you also need to consider post-tax returns.
To maximise gains, many experts advise buying gold in its electronic form, such as gold exchange-traded funds (ETFs).
If you are planning to invest in gold this Diwali purely for gains, which is the better choice: physical gold or gold ETFs?
Before deciding on which form of gold to pick, you need to have a look at the taxation of physical gold and gold ETFs.
Chintan Ghelani, Partner, Direct Tax, N.A. Shah Associates LLP, says that when you sell gold, you need to pay the short-term capital gain (STCG) or the long-term capital gain (LTCG) tax depending on the holding period. But when you buy it, you pay goods and service tax (GST) on the total transaction value.
Here’s the taxation on physical gold and gold ETFs as explained by Ghelani.
STCG and LTCG on physical gold
Physical gold can include gold jewellery, coins, bars, and bullion.
If physical gold is held for 24 months or less, the gain on sale is treated as STCG and is taxable at the individual’s applicable slab rate.
If it is held for more than 24 months, the gain qualifies as LTCG and is taxable at 12.5%, plus applicable surcharge and cess, without indexation benefit.
LTCG on gains of Rs 4 lakh from physical gold
For example, if an individual purchases gold worth Rs 10 lakh and sells it after holding it for more than two years for Rs 14 lakh, the Rs 4 lakh gain would qualify as LTCG and would be taxable at 12.5%, plus applicable surcharge and cess.
3% GST on purchase of physical gold
If you are buying physical gold from a jeweller, then the sale of finished gold is generally taxable at 3% GST on the total transaction value. This includes making charges as well, even if the value of gold and making charges are separately disclosed on the invoice.
Physical gold vs gold ETF taxation: STCG and LTCG tax
Source: Chintan Ghelani, partner, direct tax, N.A. Shah Associates LLP
Is GST applicable to physical goldsales?
Ghelani says where an individual sells personal old gold or gold jewellery to a jeweller, the transaction is generally outside the scope of GST, as the individual does not ordinarily undertake the sale in the course or furtherance of business.
Where documentation for physical gold is important
Ghelani says an important practical point is to preserve purchase invoices. In the case of inherited or gifted jewellery, documents establishing inheritance or gift and, wherever possible, the original owner’s acquisition details should also be maintained. These may become relevant both for establishing the source of the gold and for computing capital gains upon its eventual sale.
Capital gain tax on gold ETFs
Gold ETFs are listed on stock exchanges; therefore, they have a shorter holding period for determining whether the capital gain is short-term or long-term.
Under the presently applicable regime:
• If gold ETF units are held for 12 months or less, the gain is treated as STCG and is taxable at the investor’s applicable slab rate.
• If gold ETF is held for more than 12 months, the gain is LTCG taxable at 12.5%, plus applicable surcharge and cess, without indexation benefit.
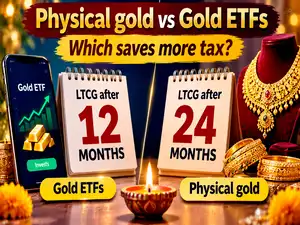
Therefore, from the capital gains tax perspective, one advantage of investing in gold ETFs is that the investment becomes a long-term capital asset after 12 months, compared to more than 24 months in the case of physical gold.
Rs 1.25 lakh annual LTCG exemption doesn’t apply on gains from gold ETFs
Ghelani says that the Rs 1.25 lakh annual LTCG exemption available in respect of specified equity shares and equity-oriented mutual funds does not apply to gold ETFs.
While gold ETFs have a shorter period for LTCG tax compared to physical gold, one can invest in either of the two or both based on their priorities and requirements.
To maximise gains, many experts advise buying gold in its electronic form, such as gold exchange-traded funds (ETFs).
If you are planning to invest in gold this Diwali purely for gains, which is the better choice: physical gold or gold ETFs?
Before deciding on which form of gold to pick, you need to have a look at the taxation of physical gold and gold ETFs.
Chintan Ghelani, Partner, Direct Tax, N.A. Shah Associates LLP, says that when you sell gold, you need to pay the short-term capital gain (STCG) or the long-term capital gain (LTCG) tax depending on the holding period. But when you buy it, you pay goods and service tax (GST) on the total transaction value.

Here’s the taxation on physical gold and gold ETFs as explained by Ghelani.
STCG and LTCG on physical gold
Physical gold can include gold jewellery, coins, bars, and bullion.
If physical gold is held for 24 months or less, the gain on sale is treated as STCG and is taxable at the individual’s applicable slab rate.
If it is held for more than 24 months, the gain qualifies as LTCG and is taxable at 12.5%, plus applicable surcharge and cess, without indexation benefit.
LTCG on gains of Rs 4 lakh from physical gold
For example, if an individual purchases gold worth Rs 10 lakh and sells it after holding it for more than two years for Rs 14 lakh, the Rs 4 lakh gain would qualify as LTCG and would be taxable at 12.5%, plus applicable surcharge and cess.
3% GST on purchase of physical gold
If you are buying physical gold from a jeweller, then the sale of finished gold is generally taxable at 3% GST on the total transaction value. This includes making charges as well, even if the value of gold and making charges are separately disclosed on the invoice.
Physical gold vs gold ETF taxation: STCG and LTCG tax
| Asset/transaction | Holding period | Tax treatment | Key point |
| Physical gold (jewellery, coins, bars and bullion) | 24 months or less | STCG; taxable at the individual's applicable income-tax slab rate. | The holding period is measured up to the date of sale. |
| Physical gold (jewellery, coins, bars and bullion) | More than 24 months | LTCG; 12.5% plus applicable surcharge and cess, without indexation. | The stated rate is before surcharge and cess. |
| Gold ETF units | 12 months or less | STCG; taxable at the investor's applicable income-tax slab rate. | Gold ETFs are listed on stock exchanges. |
| Gold ETF units | More than 12 months | LTCG; 12.5% plus applicable surcharge and cess, without indexation. | The ₹1.25 lakh equity LTCG exemption does not apply. |
| Purchase of finished physical gold from a jeweller | At purchase | Generally 3% GST on the total transaction value, including making charges. | GST applies to the total value even if gold value and making charges are separately shown. |
| Sale of personal old gold / jewellery by an individual to a jeweller | At sale | Generally outside GST, where the individual is not selling in the course or furtherance of business. | This is separate from any capital gains tax that may arise on the sale. |
Is GST applicable to physical goldsales?
Ghelani says where an individual sells personal old gold or gold jewellery to a jeweller, the transaction is generally outside the scope of GST, as the individual does not ordinarily undertake the sale in the course or furtherance of business.
Where documentation for physical gold is important
Ghelani says an important practical point is to preserve purchase invoices. In the case of inherited or gifted jewellery, documents establishing inheritance or gift and, wherever possible, the original owner’s acquisition details should also be maintained. These may become relevant both for establishing the source of the gold and for computing capital gains upon its eventual sale.
Capital gain tax on gold ETFs
Gold ETFs are listed on stock exchanges; therefore, they have a shorter holding period for determining whether the capital gain is short-term or long-term.
Under the presently applicable regime:
• If gold ETF units are held for 12 months or less, the gain is treated as STCG and is taxable at the investor’s applicable slab rate.
• If gold ETF is held for more than 12 months, the gain is LTCG taxable at 12.5%, plus applicable surcharge and cess, without indexation benefit.
Therefore, from the capital gains tax perspective, one advantage of investing in gold ETFs is that the investment becomes a long-term capital asset after 12 months, compared to more than 24 months in the case of physical gold.
Rs 1.25 lakh annual LTCG exemption doesn’t apply on gains from gold ETFs
Ghelani says that the Rs 1.25 lakh annual LTCG exemption available in respect of specified equity shares and equity-oriented mutual funds does not apply to gold ETFs.
While gold ETFs have a shorter period for LTCG tax compared to physical gold, one can invest in either of the two or both based on their priorities and requirements.
Add  as a Reliable and Trusted News Source
 Add Now!
(Catch all the Personal Finance News, Breaking News, Budget 2025 Events and Latest News Updates on The Economic Times.)
Read More News on
(Catch all the Personal Finance News, Breaking News, Budget 2025 Events and Latest News Updates on The Economic Times.)

 ETPrime Membership