
Listen to this article in summarized format
×
Subscribe to
Unlock AI Briefing and Premium Content
New Year Offer 24 Hours Left
Subscribe NowAlready a member? Sign In
What's Included
- Exclusive Stories
- Daily ePaper Access
- Smart Market Tools
- Curated Investment Ideas
- Ad-lite Experience
Subscription
 Reuters
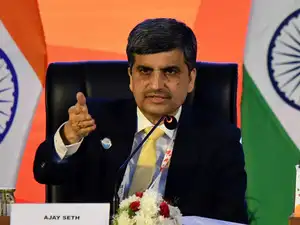
MUMBAI: India's insurance regulator will ensure an "orderly transition" to proposed reforms governing insurance sales, with no intention of disrupting insurers or distributors, its chairman Ajay Seth said on Thursday.
The Insurance Regulatory and Development Authority of India (IRDAI) last month proposed capping commissions on a range of insurance products and tightening insurers' expense limits to lower policy costs and curb mis-selling.
"The idea is to allow for an orderly transition from the present system to a better system," Seth told reporters on the sidelines of an event.
Also Read: IRDAI may allow transition period for insurance fee cap
"There's absolutely no intention that there should be a disruption for any market player or any individual."
Distributors and analysts have, however, warned that the rules could upend established business models, weigh on growth and cost jobs in an industry that relies heavily on agents and banks to sell policies.
Seth, who met insurers and distributors this week, said their requests so far have been relaxations for smaller players and low-value policies, along with a transition path.
However, no one has objected to the problems the regulator identified or the broad direction of the reforms, he said.
The rules could take effect from January or April 1 next year, depending on industry feedback, Seth said. A draft regulation will follow the consultation, giving stakeholders another chance to comment.
Brokers have sought to push the October 25 consultation deadline to late December, Reuters reported earlier this month. Seth did not commit to an extension and urged stakeholders to send their comments on time.
India is the world's 10th-largest insurance market, with $124.4 billion in premiums in fiscal 2025 across roughly 60 insurers, including Prudential and Sun Life Financial.
The proposed rules are part of the IRDAI's push to reform the sector after New Delhi this year opened it to 100% foreign ownership, and target costs it says have ballooned since commission limits were scrapped in 2023.
(You can now subscribe to our Economic Times WhatsApp channel)
The Insurance Regulatory and Development Authority of India (IRDAI) last month proposed capping commissions on a range of insurance products and tightening insurers' expense limits to lower policy costs and curb mis-selling.
"The idea is to allow for an orderly transition from the present system to a better system," Seth told reporters on the sidelines of an event.
Also Read: IRDAI may allow transition period for insurance fee cap
"There's absolutely no intention that there should be a disruption for any market player or any individual."

Distributors and analysts have, however, warned that the rules could upend established business models, weigh on growth and cost jobs in an industry that relies heavily on agents and banks to sell policies.
Seth, who met insurers and distributors this week, said their requests so far have been relaxations for smaller players and low-value policies, along with a transition path.
However, no one has objected to the problems the regulator identified or the broad direction of the reforms, he said.
The rules could take effect from January or April 1 next year, depending on industry feedback, Seth said. A draft regulation will follow the consultation, giving stakeholders another chance to comment.
Brokers have sought to push the October 25 consultation deadline to late December, Reuters reported earlier this month. Seth did not commit to an extension and urged stakeholders to send their comments on time.
India is the world's 10th-largest insurance market, with $124.4 billion in premiums in fiscal 2025 across roughly 60 insurers, including Prudential and Sun Life Financial.
The proposed rules are part of the IRDAI's push to reform the sector after New Delhi this year opened it to 100% foreign ownership, and target costs it says have ballooned since commission limits were scrapped in 2023.
Add  as a Reliable and Trusted News Source
 Add Now!
(You can now subscribe to our Economic Times WhatsApp channel)
(Catch all the Business News, Breaking News and Latest News Updates on The Economic Times.)
Subscribe to The Economic Times Prime and read the ET ePaper online.
Read More News on
(Catch all the Business News, Breaking News and Latest News Updates on The Economic Times.)
Subscribe to The Economic Times Prime and read the ET ePaper online.

 ETPrime Membership